JPMorgan and DBS launch 24/7 U.S.–Singapore dollar transfers
The banks linked their tokenized deposit networks for institutional dollar transfers. A weekend example shows where the service can save time.
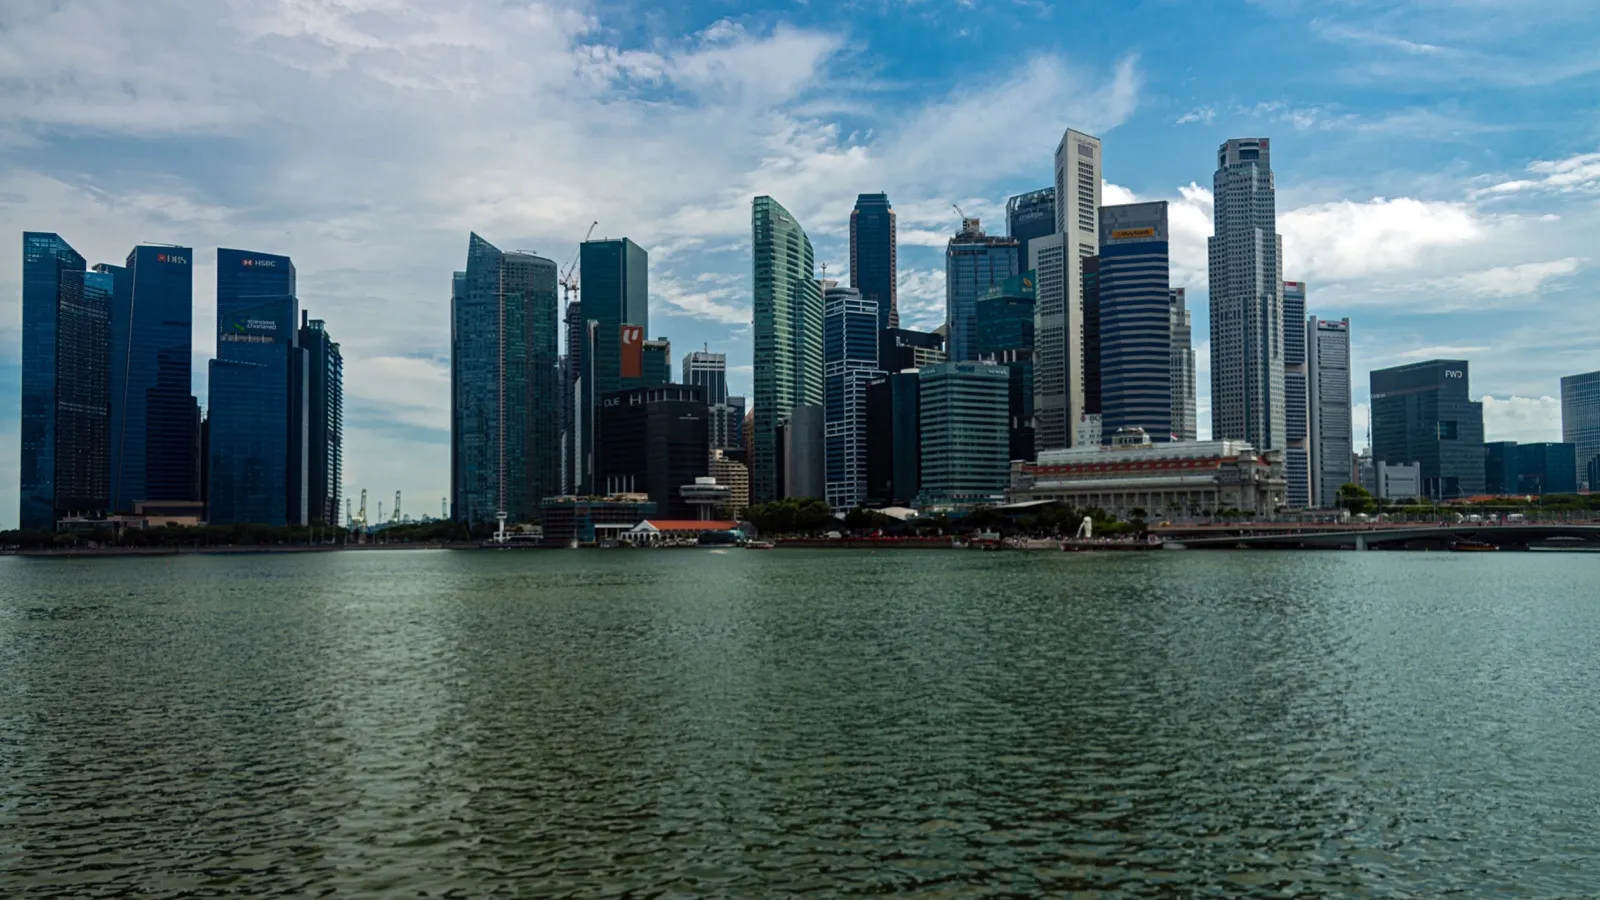
JPMorgan and DBS have linked two bank deposit networks so institutions can transfer U.S. dollars between participating accounts in the United States and Singapore around the clock. The joint announcement from Singapore on Nov. 16 says the service connects DBS Token Services with Kinexys by J.P. Morgan and can handle transfers on weekends and outside ordinary banking hours.
The change concerns a specific part of the payment route. An eligible company holding funds in one of the participating blockchain-based accounts can send dollars to a participating account on the other network without waiting for the usual business-day cutoff on that transfer. How each company gets money into the account, and what it does with that money after it arrives, can involve separate arrangements.
The banks named Ant International as the first participant. They also said Partior helps coordinate settlement between the networks. The announcement gives other institutions a working example of the route, while eligibility and onboarding determine who can use it.
What a weekend transfer could look like
Suppose an American company’s treasury team needs to move dollars to a participating account in Singapore at 7 p.m. on a Friday in November. New York is on Eastern Standard Time, five hours behind UTC, while Singapore is eight hours ahead of UTC. The 13-hour difference makes it 8 a.m. Saturday in Singapore. The banks say the linked services can execute that institutional dollar transfer even though it falls outside ordinary banking hours in both places.
That timing can help a company place funds where it needs them before staff in one country return to work on Monday. It could also help when an e-commerce company receives proceeds over a weekend or when a treasury team has to move balances to meet a deadline in another time zone. An institution still needs the relevant accounts and permissions, enough available funds, and access to the receiving end of the service.
What a tokenized deposit represents
The systems use blockchain-based records to represent deposits at the participating banks. Customers are moving value denominated in U.S. dollars through accounts in bank-operated networks. The tokenized record represents the bank deposit and lets account transfers be recorded in a way the connected networks can process. DBS describes both ecosystems as permissioned, meaning access is controlled.
Linking the systems addresses a question that comes up when banks build separate networks. A company needs to be able to reach a participant using a different bank. The Nov. 16 announcement says the two systems are now connected for this dollar route. The companies had announced a framework in November 2025 to support transfers between the ecosystems. The new announcement describes a service institutions can use, subject to its terms.
The announced route is for U.S. dollars. A business trying to end the transfer with Singapore dollars would need to account for any separate currency conversion, its cost, and when it can be performed. That is a separate timing question from whether two participating dollar accounts can communicate after hours. A treasury team comparing routes should start by specifying which currency the recipient needs, which account will hold it and when it has to be usable.
Where the timing still depends on the account
Consider three steps when judging how soon a payment can be used. The sending institution first needs funds available in its participating account. The linked networks then execute the dollar transfer. Finally, the receiving institution decides whether to keep the funds there or move them to another account or service. The round-the-clock capability described in the announcement applies to the linked network transfer. Funding and withdrawal can depend on how the account is connected to other banking systems.
For example, Kinexys’ account documentation describes a weekend maintenance window for moving money between traditional demand deposit accounts and its blockchain deposit accounts. A company planning a weekend payment would want to ask when funds have to be available in the sending account and when the recipient expects to use them outside the network. Those two answers determine whether the end-to-end timing fits the job.
The announcement establishes the banks’ claimed service scope. It leaves individual customers’ onboarding, fees, limits and account requirements to their banking arrangements. Those details are what treasury teams would need to compare this route with the payment options they already use. See Newsmerica’s Business desk for related coverage.
Trust & transparency
How we handled this story
Verified the joint Nov. 16 DBS announcement, Kinexys’ account documentation and independent industry coverage. Participant eligibility, limits, and legacy account access depend on service terms.
Grounded in this reporting
Ask Newsmerica
Ask about this article. Answers quote the closest published passages and link back to their sources.
This tool retrieves article passages; it does not add outside facts.Keep exploring
More from Newsmerica
Related coverage
Business & Economy
Black Friday 2026 dates for Walmart, Target, Best Buy and Home Depot
Business & Economy
30 states join FTC’s Dollar General lawsuit as Family Dollar deal awaits approval
Business & Economy