Supreme Court declines Custodia Bank’s Fed account appeal
The justices left an appeals court judgment in place. Here’s what the case says about a bank’s charter and direct access to Fed payment services.
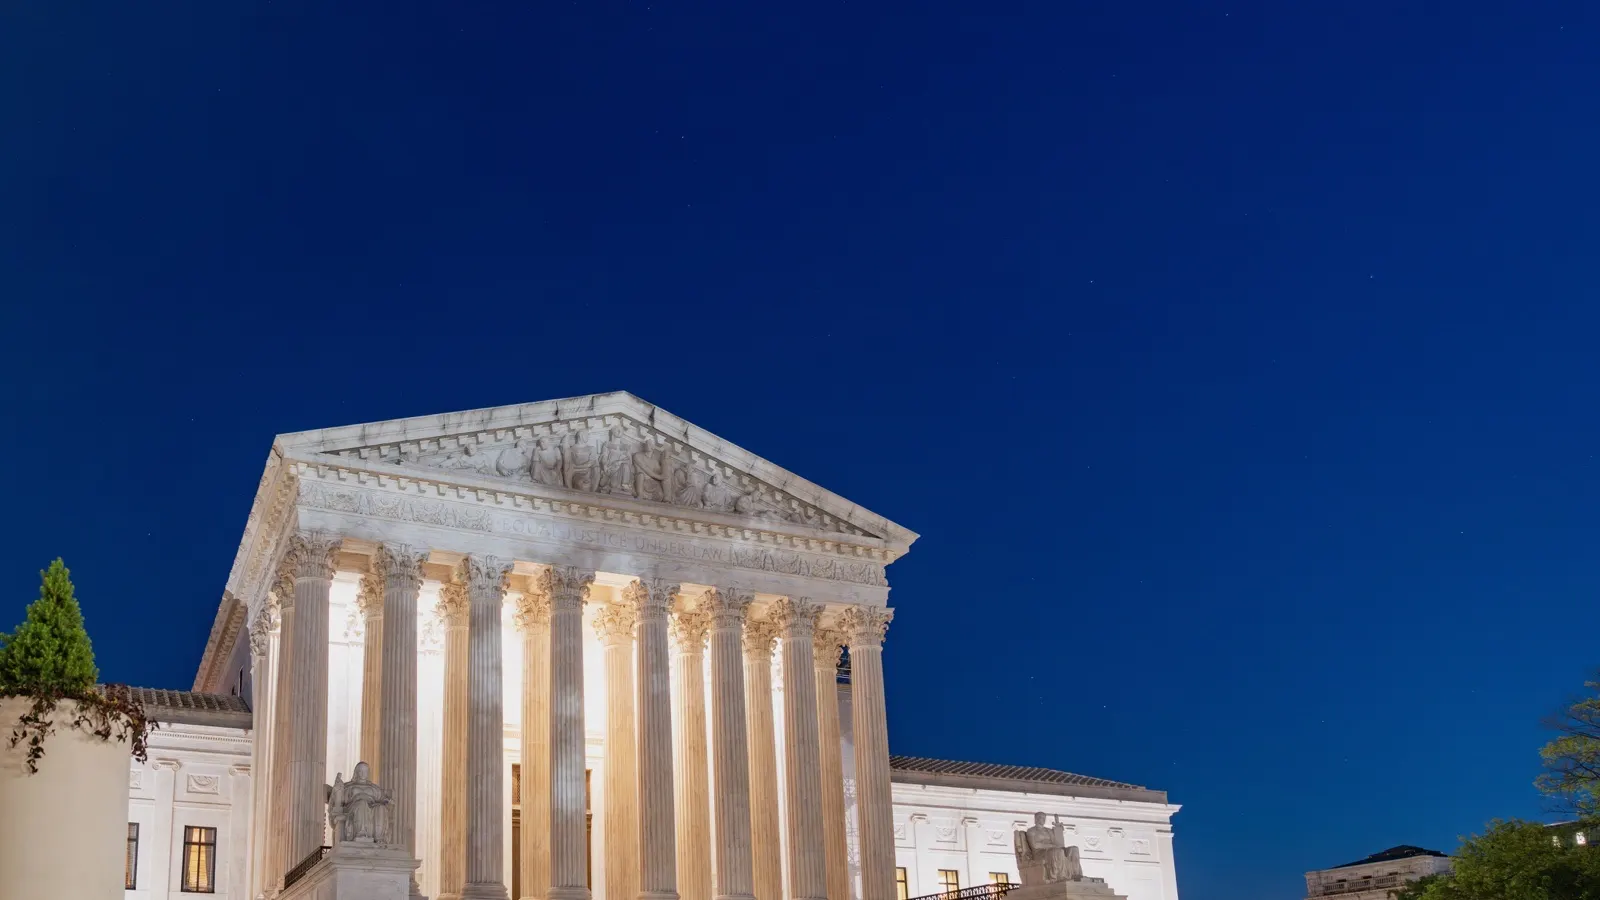
The Supreme Court declined Monday to hear Custodia Bank’s challenge over access to a Federal Reserve master account. The Nov. 16 docket entry in case No. 26-62 says the petition was denied. The order leaves in place an appeals court judgment that upheld the Federal Reserve Bank of Kansas City’s authority to reject the Wyoming bank’s application.
The case turned on a step that sits between receiving a bank charter and operating with direct access to Federal Reserve services. Wyoming authorized Custodia to operate under a state charter. Custodia argued it was entitled to a master account as an eligible institution. The Kansas City Fed’s decision and the court fight concerned who decides whether access is actually granted.
Why a master account matters
A bank charter establishes the legal basis on which an institution can conduct its banking business. A Federal Reserve master account serves a different function. It lets the institution maintain an account relationship at a reserve bank and, subject to applicable agreements and requirements, settle transactions using Federal Reserve services. The Fed’s access guidelines describe how reserve banks evaluate requests for accounts and services.
Think about a payment that has to move between financial institutions. With the relevant approvals and service arrangements, one institution can use its own Federal Reserve account to settle payments it sends and receives. An institution relying on an intermediary works through another bank that can provide the service. That relationship adds another set of terms about which payments it can process and how settlement works. The difference helps explain why direct access matters to a bank’s business plan.
That distinction also explains why a state charter and a master account appear as separate decisions in this case. The charter addresses the institution’s authority to operate. The account request raises questions about access to Federal Reserve infrastructure and the conditions attached to using it.
Indirect access also has conditions. The Fed’s account database FAQ says it applies its eligibility and other access criteria both to institutions with their own master account and to institutions settling transactions through another depository institution’s master account. That distinction matters because the route through another bank may change who holds the account and handles settlement, while the Federal Reserve still has requirements for the underlying access.
What the appeals court decided
In its Oct. 31, 2025 judgment, the U.S. Court of Appeals for the Tenth Circuit rejected Custodia’s argument that the law required its application to be approved. The appeals court concluded that reserve banks have discretion in deciding whether to grant master accounts to eligible institutions. Custodia later asked the Supreme Court to review that outcome.
Monday’s denial of review leaves the lower court’s judgment in place. Readers looking for an explanation of the governing statutes and the disagreement between the parties will find it in the Tenth Circuit opinion and the briefs. The Supreme Court’s order list records what happened to the petition. The procedural result gives the lower court’s judgment effect in this case without adding separate reasoning from the justices.
The timeline separates the courts’ roles. The appeals court issued its decision in October 2025 and denied rehearing in March 2026, according to the Supreme Court docket. Custodia filed its petition in July. Monday’s docket entry closed that request for review. It is the latest procedural step in the same dispute, and the earlier appellate opinion remains the source for how the court read the law.
What the outcome means beyond one application
The immediate result is that Custodia’s challenge did not overturn the Kansas City Fed’s decision. Other applicants can still follow the Fed’s procedures and are assessed under the applicable framework. A state charter may be part of what establishes an institution’s eligibility. The reserve bank’s evaluation is the step that determines what access it grants on that application.
For payment businesses, the practical distinction is who holds the account and who handles the movement of funds. A company may have customers and the authority to provide financial services while relying on another institution for particular payment functions. Readers following the next dispute should check the applicant’s charter, the services requested, and which reserve bank made the decision. See Newsmerica’s Business desk for related coverage of banking and payment infrastructure.
Trust & transparency
How we handled this story
Verified the Nov. 16 denial in docket No. 26-62, the Oct. 31, 2025 Tenth Circuit judgment in 24-8024, and the Federal Reserve’s account-access guidance.
Grounded in this reporting
Ask Newsmerica
Ask about this article. Answers quote the closest published passages and link back to their sources.
This tool retrieves article passages; it does not add outside facts.Keep exploring
More from Newsmerica
Related coverage
Business & Economy
Black Friday 2026 dates for Walmart, Target, Best Buy and Home Depot
Business & Economy
30 states join FTC’s Dollar General lawsuit as Family Dollar deal awaits approval
Business & Economy